ATTENTION: Self-Employed, Jumbo & Non-QM Buyers in Katy, TX (and across Texas) — Get Pre-Qualified FAST
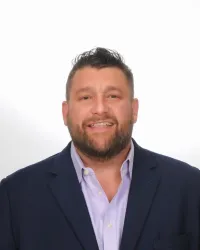
Bill Rapp, Mortgage Originator:
NMLS 228246 | Serving Katy & the Texas Region
Expertise in Self-Employed, Jumbo, & Non-QM Mortgages.
Your Texas Mortgage Specialist in Katy & Beyond!
Get Your Katy, TX Mortgage Quote (Self-Employed • Jumbo • Non-QM)
Enter your name and email to get your options and next steps:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Self-Employed, Jumbo, and Non-QM Mortgages in Katy, TX and Texas
Getting a mortgage as a self-employed borrower or through Jumbo and Non-QM programs in Katy and the wider Texas area is simpler than you might think. This guide covers what these loans are, who they help, and when they make sense.
What Is a Jumbo or Non-QM Loan?
A jumbo mortgage—also called a non-conforming loan—is any mortgage that exceeds the loan limits set by Fannie Mae and Freddie Mac.
Fannie Mae and Freddie Mac, established by Congress, support liquidity and stability in the mortgage market by buying loans that meet strict requirements for:
Loan amount
Credit score
Down payment
Debt-to-income ratio
Post-closing reserves
Loans exceeding these limits are considered non-conforming.
When Do You Need a Jumbo Loan?
You’ll need a jumbo loan when the loan amount goes above the conforming limit specific to Katy, TX, or other Texas regions.
How Jumbo and Non-QM Loans Are Underwritten
Jumbo loans use the same essential criteria as conventional loans:
Credit score
Down payment
Debt-to-income ratio (DTI)
Cash reserves after closing
However, jumbo loans often offer greater flexibility in evaluating these factors.
Credit Scores
Most jumbo programs accept credit scores starting at 660, although higher scores get better rates. Borrowers with scores above 760 generally secure the best terms.
Cash Reserves
These loans typically require more substantial reserves than conforming loans.
Standard requirement: 12 months of reserves
Reserves may be split between cash and retirement accounts
Exceptions can apply for strong income, low DTI, or sizable down payments.
Flexible Features for Self-Employed and Jumbo Loan Borrowers
Higher DTI allowances
Jumbo loans may accept higher DTI ratios if backed by strong reserves or equity.
Income Verification for Self-Employed
Self-employed applicants in Katy, TX, can often qualify with just one year of tax returns if they demonstrate stable business performance and industry experience.
Lower Down Payments Without Mortgage Insurance
Certain jumbo programs allow for as little as 10% down without mortgage insurance, with slightly higher rates and stricter DTI limits.
Piggyback Loan Options
Some buyers can combine first and second mortgages to reduce down payments to as low as 5%. These specialized options vary by lender.
Who Benefits from Jumbo and Non-QM Loans in Texas?
These loans are ideal for high-income earners and self-employed professionals in Katy and Texas who want to keep cash liquid rather than tied up in down payments. This group is often called HENRYs: High Earners, Not Rich Yet.
Typical borrowers:
Earn $250,000–$500,000+ per year
Maintain strong credit
Have significant retirement and investment assets
Prefer liquidity over large upfront cash requirements
Tax Considerations
Jumbo mortgages don’t typically offer special tax advantages.
Mortgage interest deduction applies only to the first $1 million of mortgage debt. Interest on amounts above this is not deductible.
Borrowers might compare:
One jumbo mortgage
vs.
Multiple smaller loans or alternative structures suited for Texas borrowers
Consult a tax advisor for personalized advice.
🏨 Hotel Mortgage Loans: How to Finance a Hotel or Motel 💰
🏨 Hotel Mortgage Loans: How to Finance a Hotel or Motel 💰
🚨 Hotel Financing: Why Lenders Say No to Hotels 🏨
_______________________________________________________________________________
Hotel Financing: How to Get a Loan for a Hotel or Motel
Buying a hotel or motel can be an attractive commercial real estate investment, but securing financing is often more complicated than financing an apartment building, office property, or shopping center.
Why?
Because lenders aren't simply financing real estate. They're also underwriting a hospitality business.
Hotel revenue fluctuates with occupancy, nightly room rates, tourism, business travel, seasonality, operating expenses, and local competition.
Unlike multifamily properties, where tenants typically sign longer-term leases, hotel guests might stay for only one night.
That creates a different risk profile for commercial lenders.
Whether you're purchasing a limited-service hotel, refinancing an established motel, renovating a hospitality property, or developing a new hotel, understanding how hotel mortgage loans work can help you structure a stronger financing request.
In this guide, I'll explain the primary hotel financing options, what lenders evaluate, how much equity borrowers may need, and why some hotel transactions are significantly harder to finance than others.
I'm Bill Rapp, CCIM, with CommLoan, where I help commercial real estate investors and business owners explore financing options through a nationwide commercial lending marketplace.
Why Are Hotels Harder to Finance Than Apartment Buildings?
One of the biggest differences between hotel financing and multifamily lending is income predictability.
An apartment building typically generates revenue from tenants with leases lasting six months, twelve months, or longer.
A hotel operates differently.
Every night, the property effectively has to resell its available rooms.
That makes hotel revenue more sensitive to economic conditions, travel patterns, local events, competition, and changes in consumer spending.
Consider two properties:
Property A: Multifamily Apartment Building
Purchase price: $4 million
Occupancy: 95%
Established rental history
Long-term residential leases
Relatively predictable monthly revenue
Property B: Limited-Service Hotel
Purchase price: $4 million
Occupancy: 65%
Revenue dependent on nightly bookings
Significant payroll and operating expenses
Greater exposure to travel demand and seasonality
Even though both properties have the same purchase price, a lender may view the hotel as a higher-risk transaction.
This can result in lower leverage, higher borrowing costs, additional equity requirements, and more intensive underwriting.
The key takeaway: Hotel financing depends heavily on both real estate value and business operating performance.
What Types of Hotel Mortgage Loans Are Available?
Several commercial financing programs may be available depending on the hotel, ownership structure, borrower experience, and intended use.
1. Conventional Bank Hotel Loans
Traditional banks and credit unions finance qualifying hospitality properties, particularly established hotels with consistent operating performance.
These loans are often suitable for stabilized, well-maintained properties with experienced ownership.
Typical illustrative characteristics include:
Loan-to-value ratios: Approximately 60%–75%
Amortization: Often 20–25 years
Loan terms: Frequently 3–10 years
Interest rates: Fixed or floating, depending on the lender
Recourse: Common, although structures vary
Lenders typically evaluate historical occupancy, operating income, borrower liquidity, credit quality, and hospitality management experience.
Branded properties with a recognized franchise and consistent performance may be more attractive to certain lenders than independent motels with inconsistent financial records.
However, a franchise alone does not guarantee financing approval.
2. SBA 7(a) Hotel Loans
The SBA 7(a) program can be an attractive option for eligible owner-operated hotels and motels.
Unlike conventional investment-property financing, SBA loans are designed to support qualifying operating businesses.
Potential eligible uses include:
Purchasing an existing hotel business and real estate
Refinancing eligible business debt
Renovating or improving the property
Purchasing qualifying equipment and furnishings
Providing eligible working capital
Depending on the transaction, the SBA 7(a) program may offer up to 25-year terms for real-estate-heavy financing.
The standard maximum SBA 7(a) loan amount is $5 million.
Equity requirements depend on the applicable SBA rules, business acquisition structure, and lender underwriting. A 10% equity injection is a common planning benchmark for certain acquisitions, but it is not a universal minimum for every hotel transaction.
SBA eligibility, affiliation rules, ownership, operating structure, and occupancy requirements must be reviewed carefully.
Important: SBA financing generally is not intended for passive investment real estate. The borrowing business must satisfy applicable eligibility and operating requirements.
3. SBA 504 Hotel Financing
SBA 504 financing may be another option for eligible hotel owners purchasing or improving owner-occupied commercial real estate.
A common SBA 504 structure involves:
Approximately 50% financing from a third-party lender
Up to 40% financing through a Certified Development Company
At least 10% borrower contribution in qualifying standard transactions
However, hotels often qualify as special-purpose properties, and additional equity may be required.
For certain hotel projects, the borrower contribution may increase to 15% or 20%, depending on factors such as business age and property classification.
SBA 504 financing generally supports eligible fixed assets, not ordinary working capital.
The program may be particularly useful for qualifying hotel acquisitions, renovations, and construction projects.
4. Hotel Bridge Loans
What happens if a hotel is underperforming, needs major renovations, or doesn't qualify for traditional bank financing?
A hotel bridge loan may provide an alternative.
Bridge lenders frequently consider transactions involving:
Underperforming hotels
Property improvement plans
Renovations and repositioning
Transitional occupancy
Short-term acquisition financing
Refinancing before stabilization
Bridge financing typically carries higher costs and shorter terms than conventional permanent loans.
Illustrative structures may include:
Terms of approximately 12–36 months
Interest-only payments
Lower leverage for riskier assets
Renovation reserves or controlled construction draws
A clearly documented exit strategy
A bridge loan can provide flexibility, but borrowers must evaluate refinancing risk, extension provisions, and the cost of carrying the property during renovations.
5. CMBS and Other Institutional Hotel Loans
Larger, stabilized hotels may qualify for commercial mortgage-backed securities financing or other institutional capital sources.
These programs are generally better suited for larger transactions with established operating histories.
Potential benefits include competitive long-term financing structures and, in some cases, nonrecourse provisions subject to standard carve-outs.
However, underwriting standards, reserve requirements, prepayment provisions, and minimum loan sizes can make these programs unsuitable for smaller hospitality properties.
6. Hotel Construction Financing
Building a new hotel presents additional financing challenges.
Unlike an existing property, a proposed hotel does not have an established operating history.
Lenders may evaluate:
Market feasibility studies
Projected occupancy and average daily rates
Franchise agreements
Construction budgets and contingency reserves
Sponsor development experience
Contractor qualifications
Completion guarantees
Debt service during construction
Stabilization and permanent financing plans
Construction lenders may require substantial sponsor equity, and permanent financing must be considered before construction begins.
What Do Hotel Lenders Look For?
Understanding hospitality underwriting can significantly improve your chances of obtaining financing.
1. Occupancy Rate
Occupancy measures the percentage of available rooms sold during a given period.
Occupancy Rate = Rooms Sold ÷ Rooms Available
For example, a 100-room hotel selling 65 rooms per night on average has a 65% occupancy rate.
Lenders examine historical occupancy, seasonal fluctuations, local market trends, and projected future performance.
2. Average Daily Rate (ADR)
ADR measures the average revenue earned per occupied room.
ADR = Room Revenue ÷ Rooms Sold
If a hotel generates $9,000 in daily room revenue from 75 occupied rooms, its ADR is $120.
Higher ADR can improve profitability, but only if occupancy and operating costs remain sustainable.
3. Revenue Per Available Room (RevPAR)
RevPAR combines occupancy and room pricing into one important hotel performance metric.
RevPAR = ADR × Occupancy Rate
For example:
Average Daily Rate: $120
Occupancy Rate: 70%
RevPAR: $84
RevPAR helps lenders compare hotel room revenue performance, although it does not measure operating profit or include ancillary revenue.
4. Net Operating Income (NOI)
Net operating income is a critical component of hotel financing.
NOI = Operating Revenue − Operating Expenses
For hotels, lenders analyze revenue from rooms and other operating departments, together with payroll, utilities, insurance, property taxes, maintenance, management fees, and other operating costs.
Depending on the lender, hotel underwriting may also incorporate replacement reserves, franchise expenses, and other adjustments.
Hotel NOI must be carefully distinguished from gross operating profit, EBITDA, and cash flow available for debt service.
5. Debt Service Coverage Ratio (DSCR)
DSCR measures whether the property generates sufficient qualifying cash flow to support its mortgage payments.
DSCR = Underwritten Cash Flow ÷ Annual Debt Service
Suppose a hotel generates $500,000 in annual underwritten cash flow and has annual debt payments of $400,000.
Its DSCR would be:
$500,000 ÷ $400,000 = 1.25x
Many conventional lenders may target DSCRs around 1.25x–1.40x or higher for hospitality assets, depending on transaction risk and underwriting standards.
A lower DSCR may require additional equity, reduced loan proceeds, or an alternative financing structure.
6. Borrower Experience and Liquidity
Hotel ownership requires active operational oversight.
Lenders may evaluate:
Prior hospitality ownership or management experience
Personal and business credit
Liquidity after closing
Net worth and contingent liabilities
Franchise or management relationships
Capital reserves
Business plans and operating forecasts
An experienced hospitality operator may have financing advantages over a first-time hotel buyer, although other factors remain important.
How Much Down Payment Do You Need for a Hotel?
Hotel down payment requirements depend on the financing program, property performance, and borrower qualifications.
Financing Type | Illustrative Equity Requirement |
Conventional bank financing | 25%–40% |
SBA 7(a) | Often 10% or more for applicable acquisitions |
SBA 504 | Commonly 10%–20% or more, depending on project |
Bridge financing | Often 25%–40% or more |
Hotel construction | Frequently 25%–40% or more |
These are broad planning ranges, not lender quotes or guaranteed program terms.
Closing costs, renovation expenses, franchise requirements, operating reserves, and other project costs can increase the total cash investment.
Real-World Example: Financing a $4 Million Hotel
Let's consider a hypothetical hotel acquisition.
Property: 80-room limited-service hotel
Purchase Price: $4,000,000
Occupancy: 68%
Average Daily Rate: $125
Annual Room Revenue Estimate:
80 rooms × 365 days × 68% occupancy × $125 ADR = $2,482,000
Now assume the property generates $650,000 in annual lender-adjusted cash flow after operating expenses and applicable underwriting adjustments.
A lender offers:
Loan amount: $2,800,000
Loan-to-value: 70%
Interest rate: 7.50% (illustrative)
Amortization: 25 years
The approximate monthly principal and interest payment would be $20,690.
Annual debt service would be approximately $248,300.
DSCR = $650,000 ÷ $248,300 = 2.62x
On these assumptions, debt service coverage appears strong.
However, the lender must still evaluate whether the property's $4 million valuation is supportable, whether historical earnings justify the $650,000 cash flow assumption, and whether franchise, renovation, management, or capital expenditure obligations could reduce available cash flow.
The borrower would also need at least $1.2 million toward the purchase price, plus applicable closing costs and reserves.
This illustrates an important principle:
Strong cash flow helps, but hotel financing approval depends on the complete transaction—not just one financial ratio.
Why Do Hotel Loans Get Declined?
Hotel financing requests can be declined for several reasons.
1. Weak or inconsistent operating income
The hotel may not generate enough sustainable cash flow to support the proposed loan.
2. Insufficient borrower liquidity
Lenders may require meaningful cash reserves after closing.
3. Deferred maintenance or franchise renovation requirements
A required property improvement plan, commonly called a PIP, may create substantial additional capital needs.
4. Limited hospitality experience
Some lenders prefer borrowers with established hotel management experience.
5. Property location or market concerns
A hotel in a market with declining travel demand or significant new competition may face tighter underwriting.
6. Incomplete financial documentation
Missing operating statements, occupancy records, franchise agreements, or tax returns can delay or prevent financing approval.
7. Loan structure does not match the property
A transitional motel may need bridge financing rather than a conventional bank mortgage.
A bank declining a hotel loan does not necessarily mean the property is unfinanceable.
It may mean the transaction needs a different capital source or structure.
Documents Needed for a Hotel Mortgage Loan
Before approaching lenders, prepare a comprehensive hospitality financing package.
Common requirements include:
Three years of business financial statements and tax returns, when available
Trailing 12-month operating statement
Year-to-date profit and loss statement
Monthly occupancy, ADR, and RevPAR reports
Historical room revenue and operating expense reports
Current franchise agreement, if applicable
Property improvement plan and renovation budget
Purchase contract or existing mortgage statement
Personal financial statement
Borrower and guarantor credit information
Schedule of real estate owned
Business ownership and entity documents
Management experience and business plan
Available property condition and environmental reports
A well-organized package allows lenders to evaluate the transaction more efficiently and can reduce avoidable delays.
How to Improve Your Chances of Getting a Hotel Loan
Here are five practical strategies.
First, organize your operating financials. Demonstrate actual historical performance instead of relying exclusively on optimistic projections.
Second, calculate realistic cash flow and debt service coverage. Account for franchise fees, staffing, property taxes, insurance, capital reserves, and necessary improvements.
Third, document your hospitality experience. If you're a first-time owner, consider whether a qualified third-party management company can strengthen your operating plan.
Fourth, prepare for the property's capital needs. Renovation requirements and deferred maintenance should be incorporated into your total project budget.
Fifth, compare financing structures before committing to one lender. Conventional banks, SBA lenders, bridge lenders, and institutional capital providers have different eligibility requirements and risk appetites.
How CommLoan Helps Hotel Investors Explore Financing Options
Finding the right hotel mortgage loan can require evaluating several different lending programs.
At CommLoan, I work with investors and business owners to help assess potential financing structures for qualifying commercial real estate transactions.
Through CommLoan's commercial lending marketplace, borrowers can explore multiple capital sources rather than relying exclusively on a single bank's lending guidelines.
Depending on the transaction, options may include conventional commercial mortgages, SBA financing, bridge loans, and other specialized hospitality lending programs.
The objective is to identify a financing structure that aligns with the property's operating performance, business plan, borrower qualifications, and long-term investment strategy.
Frequently Asked Questions About Hotel Financing
Can you get a mortgage to buy a hotel?
Yes. Qualified borrowers can obtain commercial hotel mortgage loans through banks, SBA lenders, and other commercial financing providers.
Is it harder to finance a motel than a hotel?
It can be. Independent motels may face additional scrutiny if they have limited financial records, weaker operating performance, or fewer recognized brand affiliations. However, a profitable, well-managed independent motel may still qualify for financing.
Can I buy a hotel with an SBA loan?
Potentially. An eligible operating business may qualify for SBA 7(a) or 504 financing, subject to program requirements and lender approval.
What credit score do you need for hotel financing?
There is no universal credit score requirement across all hotel mortgage programs. Credit expectations depend on the lender, loan type, and overall borrower profile.
Can you refinance an existing hotel?
Yes. Depending on eligibility, owners may refinance through conventional lenders, SBA programs, bridge lenders, or institutional capital sources.
Can a first-time hotel buyer qualify for financing?
Yes, although lenders may place greater emphasis on management experience, borrower liquidity, equity contribution, and the strength of the operating plan.
Are hotel mortgage loans available for independent motels?
Yes. Independent properties can qualify, but lenders may apply different underwriting standards than they use for established franchise properties.
Final Thoughts: Choose the Right Hotel Financing Strategy
Hotel and motel financing is fundamentally different from many other commercial real estate loans.
Lenders evaluate the physical property, operating business, borrower qualifications, market demand, and the sustainability of hotel revenue.
A profitable, stabilized hotel may qualify for conventional financing.
An eligible owner-operated hospitality business may benefit from SBA financing.
A property requiring renovations or repositioning may need bridge capital before qualifying for permanent financing.
The right financing strategy starts with understanding the hotel—not simply shopping for the lowest interest rate.
If you're purchasing, refinancing, renovating, or developing a hotel or motel, I can help you explore available commercial financing options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Serving Katy, TX & all of Texas
Call or email for a fast pre-qualification for self-employed, jumbo, and Non-QM loans.
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302 Las Vegas, NV 89141