ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
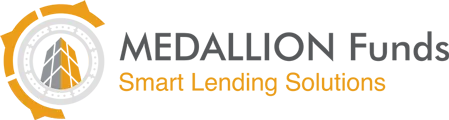
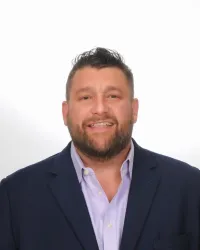
Bill Rapp, Mortgage Originator:
NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Jumbo and Non-QM Mortgages: Made Simple
Getting a jumbo or Non-QM mortgage is easier than most people expect. This guide explains what these loans are, who they’re for, and when they make sense.
What Is a Jumbo or Non-QM Loan?
A jumbo mortgage—also called a non-conforming loan—is any mortgage that does not meet the guidelines set by Fannie Mae and Freddie Mac.
Fannie Mae and Freddie Mac were created by Congress to provide liquidity and stability in the mortgage market. They buy mortgages from lenders, but only if those loans meet strict rules for:
Loan amount
Credit score
Down payment
Debt-to-income ratio
Post-closing reserves
Loans that exceed these limits are considered non-conforming.
When Do You Need a Jumbo Loan?
You’ll need a jumbo loan when the loan amount exceeds the conforming limit in your area.
How Jumbo and Non-QM Loans Are Underwritten
Jumbo loans are evaluated using the same fundamentals as conventional loans:
Credit score
Down payment
Debt-to-income ratio (DTI)
Cash reserves after closing
That said, jumbo loans often allow more flexibility in how those factors are evaluated.
Credit Scores
Most jumbo programs are available with credit scores as low as 660, though higher scores receive better rates. Borrowers with 760+ credit generally receive the most favorable terms.
Cash Reserves
Jumbo loans usually require more reserves than conforming loans.
Typical requirement: 12 months of reserves
Often split between liquid cash and retirement assets
Exceptions may be available with strong income, low DTI, or large down payments.
Where Jumbo Loans Are More Flexible
Higher DTI allowances
While conforming loans often cap DTI around 43%, jumbo loans may allow higher ratios if the borrower has strong reserves or equity.
More logical income analysis
Self-employed borrowers may qualify with one year of tax returns instead of two if they can document business stability and industry experience.
Lower down payments without mortgage insurance
Some jumbo programs allow 10% down—and sometimes less—without mortgage insurance. Rates may be slightly higher, and DTI requirements are typically stricter.
Piggyback loan structures
In certain cases, buyers can combine a first and second mortgage to reduce the down payment to as little as 5%. These structures are highly specialized and lender-specific.
Who Typically Uses Jumbo or Non-QM Loans?
These loans are well-suited for high-income earners who don’t want—or don’t have—their wealth tied up in cash. This group is often referred to as HENRYs: High Earners, Not Rich Yet.
HENRY borrowers often:
Earn $250,000–$500,000+ annually
Have strong credit histories
Hold significant retirement and investment assets
Prefer liquidity over tying up cash in a large down payment
Tax Considerations
Jumbo loans don’t automatically create tax advantages.
Mortgage interest is only deductible on the first $1 million of mortgage debt. If your loan exceeds that amount, the interest on the excess is not deductible.
For this reason, some borrowers choose to compare:
One jumbo loan
vs.
Two smaller loans or alternative structures
Always consult a tax professional before assuming tax benefits.
Choosing the Right Professionals
Buying a home—especially with a jumbo or Non-QM loan—is complex. You should always work with professionals who represent your interests, not just the transaction.
Real Estate Representation
Seller’s agents represent the seller
Buyer’s agents represent the buyer
Transaction brokers represent no one
As a buyer, it’s almost always best to work with a buyer’s agent who has a legal duty to protect your interests.
Mortgage Broker vs. Bank
A mortgage broker typically has access to many lenders, not just one bank’s in-house programs. This often results in:
Better pricing
More flexible loan options
Specialized programs banks may not offer
Even if you like your bank, remember: most banks sell loans shortly after closing anyway. Loyalty should never cost you better terms.
Foreign National Mortgages
You do not need to be a U.S. citizen to qualify for a mortgage.
Eligible Borrowers
Permanent residents (green card holders)
Non-permanent residents with valid work authorization
Refugees or individuals granted asylum
Non-resident foreign buyers may also qualify, but usually with:
Higher down payments (30–50%)
Higher interest rates
Fewer program options
Legal residency and proper documentation are mandatory.
Bank Statement Loans for Self-Employed Borrowers
If you’re self-employed and traditional tax returns don’t reflect your true income, a bank statement mortgage may be the solution.
How They Work
Instead of W-2s or tax returns, lenders use 12–24 months of bank statements to calculate income based on actual deposits.
Ideal For:
Business owners
Independent contractors
Freelancers and gig workers
Borrowers with significant tax write-offs
Trade-Offs
Because these loans are considered Non-QM:
Rates are typically higher
Down payments may be larger
Terms vary widely by lender, so shopping matters.
Final Thought
If you’ve been told “no” by a bank or lender, it doesn’t mean you can’t qualify—it often means you’re speaking with the wrong person.
In real estate and lending, who you work with matters.
Questions About Jumbo, Non-QM, or Bank Statement Loans?
Schedule a free, no-obligation consultation with a mortgage expert who knows how to structure complex deals efficiently.
Contact the Mortgage Viking
📞 281-222-0433
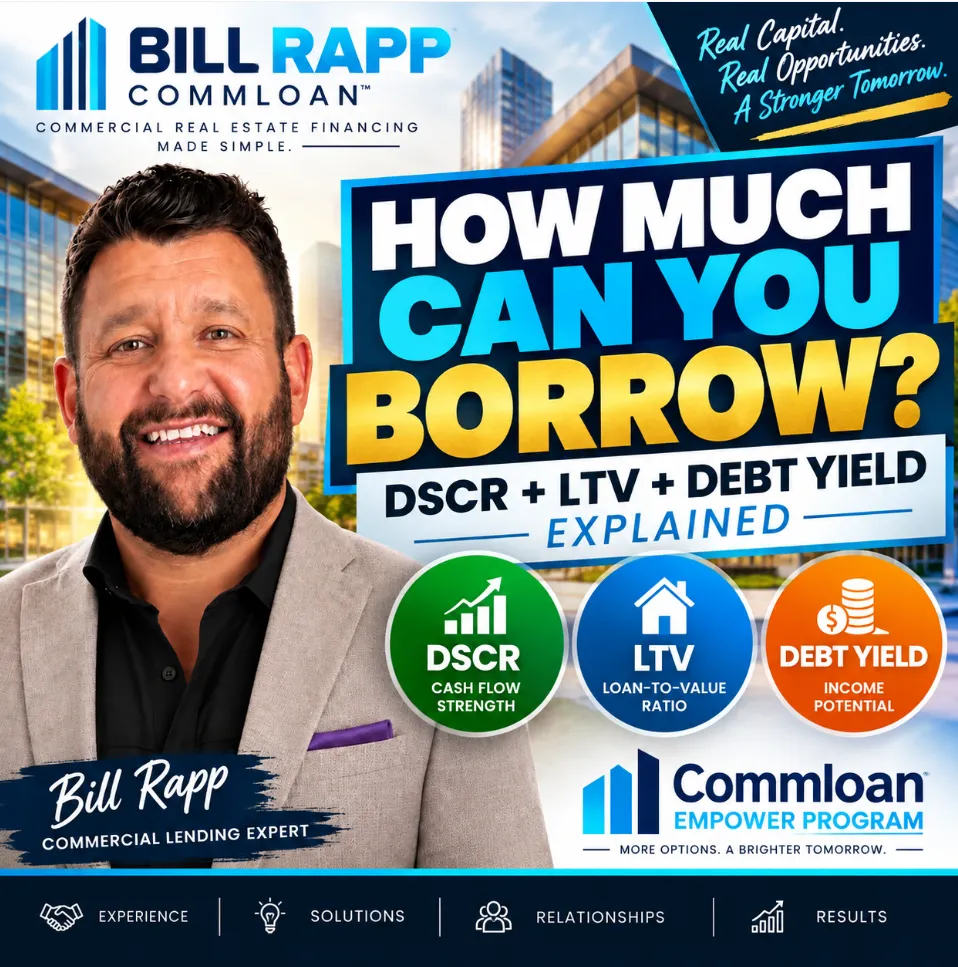
🏢 How Much Can You Borrow on Commercial Real Estate? DSCR, LTV & Debt Yield Explained 💰
🏢 How Much Can You Borrow on Commercial Real Estate? DSCR, LTV & Debt Yield Explained 💰
📊 Commercial Real Estate Loan Sizing: How DSCR, LTV & Debt Yield Determine Your Maximum Loan 🏦
How Much Can You Borrow? DSCR + LTV + Debt Yield Explained
How Much Can You Borrow? DSCR + LTV + Debt Yield Explained
When commercial real estate investors ask, “How much can I borrow?”, there usually isn't one simple answer.
Unlike many residential mortgages, where borrower income and debt-to-income ratios play a major role, commercial real estate lenders often focus heavily on the economics of the property itself.
Three calculations frequently determine how much financing a commercial property can support:
DSCR — Debt Service Coverage Ratio
LTV — Loan-to-Value Ratio
Debt Yield
Understanding these three commercial real estate lending metrics can help you estimate loan proceeds before approaching a lender—and understand why the loan amount a lender offers may be lower than you expected.
What Determines How Much You Can Borrow on Commercial Real Estate?
Commercial lenders typically evaluate several factors, including:
·Property net operating income
·Property value
·Requested loan amount
·Annual debt service
·Interest rate
·Amortization period
·Property type
·Occupancy and tenant quality
·Lease rollover
·Borrower liquidity and net worth
·Sponsor experience
·Market conditions
But DSCR, LTV and debt yield are three of the most important measurements used to size many commercial real estate loans.
The important point is this:
The maximum loan isn't necessarily determined by the metric that looks best. It can be determined by whichever underwriting constraint produces the lowest acceptable loan amount.
Let's examine each one.
1. What Is DSCR?
Debt Service Coverage Ratio (DSCR) measures a property's ability to generate enough net operating income to cover its required loan payments.
The basic formula is:
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose an investment property produces $150,000 of annual NOI and the proposed mortgage requires $120,000 of annual principal and interest payments.
The DSCR would be:
$150,000 ÷ $120,000 = 1.25x DSCR
A 1.25x DSCR means the property generates $1.25 of NOI for every $1.00 of annual debt service.
Why DSCR Matters
Lenders want a cushion between property income and required debt payments.
A property operating at exactly 1.00x DSCR would theoretically generate only enough NOI to make its debt payments, leaving no underwriting cushion if revenue declines or expenses increase.
Required DSCR varies by lender, property type, transaction and market conditions.
That's why borrowers should never assume that one DSCR requirement applies to every commercial loan.
How Interest Rates Affect DSCR Loan Proceeds
DSCR also explains why rising interest rates can reduce borrowing capacity even when a property's NOI hasn't changed.
Consider a property generating the same $150,000 NOI.
If a lender requires a 1.25x DSCR, maximum annual debt service would be:
$150,000 ÷ 1.25 = $120,000
The loan amount supported by that $120,000 payment depends on the interest rate and amortization schedule.
Higher rates generally mean the same annual debt-service allowance supports less principal.
This is one reason commercial real estate investors can encounter a refinancing gap at maturity.
The property's income may still be healthy, but today's interest rate may not support the outstanding loan balance under the lender's DSCR requirement.
2. What Is LTV?
Loan-to-Value Ratio (LTV) compares the loan amount with the lender's accepted property value.
The formula is:
LTV = Loan Amount ÷ Property Value
For example, assume a property is valued at $2,000,000 and the requested loan is $1,400,000.
The LTV is:
$1,400,000 ÷ $2,000,000 = 70% LTV
From another perspective, if a lender permits a maximum 70% LTV on a $2 million property, the leverage-based maximum would be:
$2,000,000 × 70% = $1,400,000
Simple enough—but there is an important catch.
LTV Does Not Guarantee the Loan Amount
Borrowers sometimes make the mistake of assuming:
“The lender offers 75% LTV, so I can borrow 75% of the property's value.”
Not necessarily.
The loan still has to satisfy the lender's other underwriting requirements.
Imagine a $2 million property with a 75% maximum LTV.
That would theoretically allow:
$2,000,000 × 75% = $1,500,000
But what if the property's NOI only supports a $1.25 million loan under the lender's DSCR requirement?
The borrower may be limited to approximately $1.25 million despite the higher LTV threshold.
Maximum LTV is a ceiling—not a promise of proceeds.
3. What Is Debt Yield?
Debt yield measures the property's NOI relative to the loan amount.
The formula is:
Debt Yield = NOI ÷ Loan Amount
Suppose a property generates $150,000 of NOI and the requested commercial mortgage is $1,500,000.
Debt yield would be:
$150,000 ÷ $1,500,000 = 10%
Debt yield gives lenders another way to evaluate leverage and risk.
Unlike DSCR, debt yield is not directly dependent on the interest rate or amortization period.
That makes it useful as a relatively straightforward measure of how much property income exists relative to the lender's principal exposure.
Reverse the Debt Yield Formula to Estimate Loan Proceeds
Debt yield can also be used to estimate maximum loan proceeds.
Assume:
NOI = $150,000
Required Debt Yield = 10%
Then:
Maximum Loan = NOI ÷ Required Debt Yield
$150,000 ÷ 10% = $1,500,000
If the lender instead required a 12% debt yield:
$150,000 ÷ 12% = $1,250,000
Same property. Same NOI.
But the more conservative debt-yield requirement reduces potential proceeds by $250,000.
DSCR vs. LTV vs. Debt Yield: Which One Determines Your Loan Amount?
Potentially all three.
Consider this simplified example.
A commercial investor owns a property valued at $3 million with $210,000 in annual NOI.
After applying its underwriting requirements, suppose a lender determines:
LTV allows: $2,100,000
DSCR supports: $1,850,000
Debt yield supports: $1,750,000
Which loan amount matters?
The debt-yield constraint is the most restrictive in this simplified scenario.
That means a borrower expecting approximately $2.1 million based solely on LTV could be surprised when the lender's underwriting produces substantially lower proceeds.
This is why sophisticated commercial financing analysis should evaluate multiple constraints before a borrower starts negotiating a transaction.
Why NOI Is So Important
Notice that both DSCR and debt yield depend directly on Net Operating Income.
That makes accurate NOI underwriting critical.
Commercial lenders may examine:
·Historical operating statements
·Trailing-12-month financials
·Current rent rolls
·Existing leases
·Contractual rent
·Vacancy
·Concessions
·Property taxes
·Insurance
·Repairs and maintenance
·Management expenses
·Replacement reserves
·Nonrecurring income and expenses
The borrower's stated NOI and the lender's underwritten NOI aren't always identical.
A lender may adjust revenue or expenses when determining sustainable cash flow.
A seemingly small NOI adjustment can materially change borrowing capacity.
Why Commercial Loan Quotes Can Vary Between Lenders
Another important point for investors and business owners is that different lenders can analyze the same transaction differently.
A bank, credit union, CMBS lender, debt fund or other capital source may have different requirements for:
·Minimum DSCR
·Maximum LTV
·Minimum debt yield
·Amortization
·Recourse
·Liquidity
·Net worth
·Property type
·Occupancy
·Loan size
·Sponsor experience
·Geographic concentration
This means the question isn't simply:
“Can I get a commercial loan?”
A better question is:
“Which capital source provides the best combination of proceeds, pricing, structure and execution for this particular property and borrower?”
Owner-Occupied Commercial Real Estate Can Be Different
DSCR, LTV and debt yield are especially important concepts in investment-property lending, but owner-occupied commercial real estate can be underwritten differently.
For an owner-user property, the lender may place greater emphasis on the operating company's cash flow and global debt-service ability in addition to collateral value.
SBA financing can introduce another set of eligibility and underwriting considerations.
The correct financing analysis therefore depends on both the property and the transaction structure.
How to Estimate Your Commercial Real Estate Borrowing Capacity
Before requesting financing, assemble the information needed to perform an initial loan-sizing analysis.
At minimum, an investor should know:
1.Current or projected NOI
2.Estimated property value or purchase price
3.Existing debt balance, if refinancing
4.Requested loan amount
5.Property type
6.Occupancy
7.Major lease expirations
8.Borrower liquidity and net worth
9.Desired loan term
10.Purpose of the financing
From there, you can evaluate the transaction through multiple underwriting lenses instead of relying solely on a target LTV.
The Bottom Line
When asking how much you can borrow on commercial real estate, don't look at LTV alone.
Think in terms of three underwriting tests:
DSCR asks: Does the property generate enough cash flow to service the debt?
LTV asks: How much leverage is being placed against the property's value?
Debt yield asks: How much NOI does the lender receive relative to its loan exposure?
The interaction among these metrics helps determine how much debt a property can realistically support.
And because lenders have different credit policies, a deal that doesn't fit one lender's parameters may fit another lender's structure differently.
Need Help Evaluating a Commercial Real Estate Loan?
Before approaching the market, it can be useful to determine how your transaction looks from a lender's perspective.
I work with commercial real estate investors and business owners to evaluate financing scenarios, analyze potential loan proceeds and compare capital sources.
Bill Rapp | CommLoan Empower Program
Commercial real estate financing should begin with the numbers—not with a guess about how much a lender will provide.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice