ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
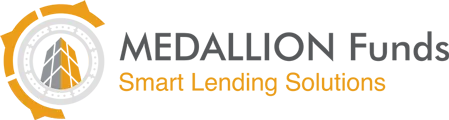
Bill Rapp, Mortgage Originator:
NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
Jumbo and Non-QM Mortgages: Made Simple
Getting a jumbo or Non-QM mortgage is easier than most people expect. This guide explains what these loans are, who they’re for, and when they make sense.
What Is a Jumbo or Non-QM Loan?
A jumbo mortgage—also called a non-conforming loan—is any mortgage that does not meet the guidelines set by Fannie Mae and Freddie Mac.
Fannie Mae and Freddie Mac were created by Congress to provide liquidity and stability in the mortgage market. They buy mortgages from lenders, but only if those loans meet strict rules for:
Loan amount
Credit score
Down payment
Debt-to-income ratio
Post-closing reserves
Loans that exceed these limits are considered non-conforming.
When Do You Need a Jumbo Loan?
You’ll need a jumbo loan when the loan amount exceeds the conforming limit in your area.
How Jumbo and Non-QM Loans Are Underwritten
Jumbo loans are evaluated using the same fundamentals as conventional loans:
Credit score
Down payment
Debt-to-income ratio (DTI)
Cash reserves after closing
That said, jumbo loans often allow more flexibility in how those factors are evaluated.
Credit Scores
Most jumbo programs are available with credit scores as low as 660, though higher scores receive better rates. Borrowers with 760+ credit generally receive the most favorable terms.
Cash Reserves
Jumbo loans usually require more reserves than conforming loans.
Typical requirement: 12 months of reserves
Often split between liquid cash and retirement assets
Exceptions may be available with strong income, low DTI, or large down payments.
Where Jumbo Loans Are More Flexible
Higher DTI allowances
While conforming loans often cap DTI around 43%, jumbo loans may allow higher ratios if the borrower has strong reserves or equity.
More logical income analysis
Self-employed borrowers may qualify with one year of tax returns instead of two if they can document business stability and industry experience.
Lower down payments without mortgage insurance
Some jumbo programs allow 10% down—and sometimes less—without mortgage insurance. Rates may be slightly higher, and DTI requirements are typically stricter.
Piggyback loan structures
In certain cases, buyers can combine a first and second mortgage to reduce the down payment to as little as 5%. These structures are highly specialized and lender-specific.
Who Typically Uses Jumbo or Non-QM Loans?
These loans are well-suited for high-income earners who don’t want—or don’t have—their wealth tied up in cash. This group is often referred to as HENRYs: High Earners, Not Rich Yet.
HENRY borrowers often:
Earn $250,000–$500,000+ annually
Have strong credit histories
Hold significant retirement and investment assets
Prefer liquidity over tying up cash in a large down payment
Tax Considerations
Jumbo loans don’t automatically create tax advantages.
Mortgage interest is only deductible on the first $1 million of mortgage debt. If your loan exceeds that amount, the interest on the excess is not deductible.
For this reason, some borrowers choose to compare:
One jumbo loan
vs.
Two smaller loans or alternative structures
Always consult a tax professional before assuming tax benefits.
Choosing the Right Professionals
Buying a home—especially with a jumbo or Non-QM loan—is complex. You should always work with professionals who represent your interests, not just the transaction.
Real Estate Representation
Seller’s agents represent the seller
Buyer’s agents represent the buyer
Transaction brokers represent no one
As a buyer, it’s almost always best to work with a buyer’s agent who has a legal duty to protect your interests.
Mortgage Broker vs. Bank
A mortgage broker typically has access to many lenders, not just one bank’s in-house programs. This often results in:
Better pricing
More flexible loan options
Specialized programs banks may not offer
Even if you like your bank, remember: most banks sell loans shortly after closing anyway. Loyalty should never cost you better terms.
Foreign National Mortgages
You do not need to be a U.S. citizen to qualify for a mortgage.
Eligible Borrowers
Permanent residents (green card holders)
Non-permanent residents with valid work authorization
Refugees or individuals granted asylum
Non-resident foreign buyers may also qualify, but usually with:
Higher down payments (30–50%)
Higher interest rates
Fewer program options
Legal residency and proper documentation are mandatory.
Bank Statement Loans for Self-Employed Borrowers
If you’re self-employed and traditional tax returns don’t reflect your true income, a bank statement mortgage may be the solution.
How They Work
Instead of W-2s or tax returns, lenders use 12–24 months of bank statements to calculate income based on actual deposits.
Ideal For:
Business owners
Independent contractors
Freelancers and gig workers
Borrowers with significant tax write-offs
Trade-Offs
Because these loans are considered Non-QM:
Rates are typically higher
Down payments may be larger
Terms vary widely by lender, so shopping matters.
Final Thought
If you’ve been told “no” by a bank or lender, it doesn’t mean you can’t qualify—it often means you’re speaking with the wrong person.
In real estate and lending, who you work with matters.
Questions About Jumbo, Non-QM, or Bank Statement Loans?
Schedule a free, no-obligation consultation with a mortgage expert who knows how to structure complex deals efficiently.
Contact the Mortgage Viking
📞 281-222-0433
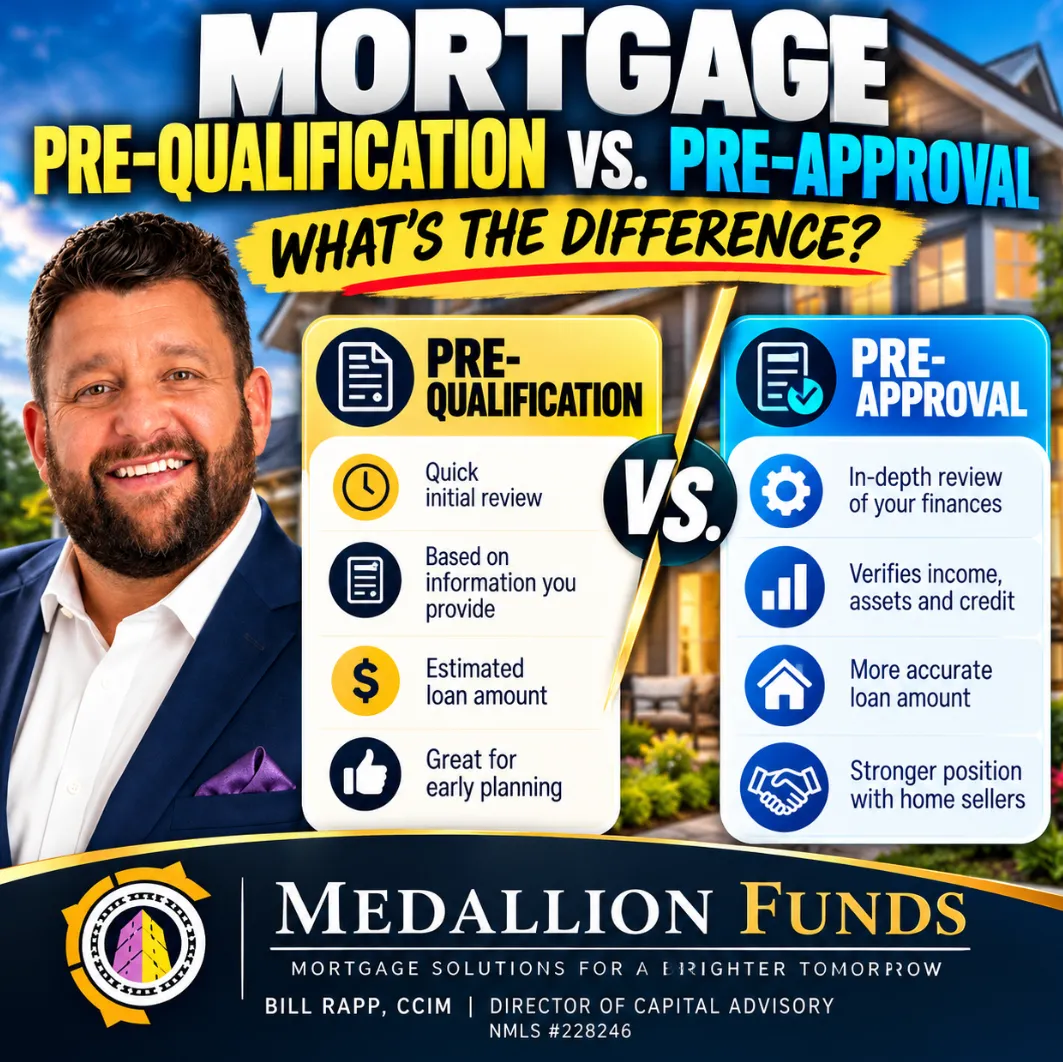
🏡 Mortgage Pre-Qualification vs. Pre-Approval: 7 Key Differences Every Homebuyer Should Know! 🔑
🏡 Mortgage Pre-Qualification vs. Pre-Approval: 7 Key Differences Every Homebuyer Should Know! 🔑
🚨 Pre-Qualified or Pre-Approved? Don't Make an Offer on a Home Until You Know the Difference! 🏠
________________________________________________________________________________
Mortgage Pre-Qualification vs. Pre-Approval: What's the Difference?
Meta Description: Learn the difference between mortgage pre-qualification and pre-approval, what lenders verify, and how to prepare to buy a home with confidence.
By Bill Rapp, CCIM | Director of Capital Advisory | Medallion Funds
Buying a home is one of the largest financial decisions most people will ever make. Before you start touring properties, however, there's an important question you need to answer:
Are you mortgage pre-qualified, or are you actually pre-approved?
These two terms are frequently used interchangeably, but they can represent very different levels of financial review.
Understanding the difference between mortgage pre-qualification and pre-approval can help you establish a realistic budget, avoid unnecessary delays, and potentially strengthen your offer when you find the right property.
At Medallion Funds, we help homebuyers evaluate mortgage options and prepare for the financing process so they can make informed decisions.
What Is Mortgage Pre-Qualification?
Mortgage pre-qualification is typically an initial assessment of how much money you may be able to borrow based on information you provide to a lender or mortgage broker.
The process often involves discussing:
·Your estimated annual income
·Your monthly debt obligations
·Your approximate credit profile
·Available savings and other assets
·Your anticipated down payment
·Your target home purchase price
Depending on the lender, pre-qualification may involve a soft credit inquiry, a more detailed credit review, or no credit check at all.
Advantages of Mortgage Pre-Qualification
1. Quick initial assessment
Pre-qualification can provide an early estimate of your borrowing capacity.
2. Helps establish a preliminary budget
Understanding your estimated purchasing power can help narrow your property search.
3. Identifies potential financing obstacles
A mortgage professional may identify issues involving income, credit, debt, or available funds before you begin making offers.
4. Useful for early financial planning
If you're considering purchasing a home several months from now, pre-qualification can help you develop a financing strategy.
Limitations of Pre-Qualification
Because pre-qualification may rely primarily on self-reported information, it does not necessarily confirm that you satisfy a lender's underwriting requirements.
Your actual mortgage eligibility could change once your financial documentation and credit history are reviewed.
Bottom line: Pre-qualification is a useful starting point, but it should not automatically be treated as a verified lending decision.
What Is Mortgage Pre-Approval?
Mortgage pre-approval generally involves a more detailed assessment of your financial qualifications.
During this process, a mortgage lender or broker typically reviews supporting information such as:
·Credit history and credit scores
·Employment and income documentation
·Bank statements and available assets
·Existing debts and financial obligations
·Down payment and closing cost funds
·Applicable mortgage program requirements
Some lenders also provide pre-approvals involving automated underwriting or an initial underwriter review.
However, the depth of verification varies by lender.
A pre-approval letter usually indicates that, based on the information reviewed, you appear eligible for financing up to a specified amount, subject to applicable conditions.
Why Mortgage Pre-Approval Matters
1. Greater confidence in your purchasing budget
A more comprehensive financial review can help identify the mortgage amount and loan structure that may fit your circumstances.
2. Stronger positioning with home sellers
A seller may view an offer accompanied by a credible pre-approval letter more favorably than an offer without evidence of financing preparation.
3. Earlier identification of underwriting issues
Income documentation, credit concerns, and asset requirements can sometimes be addressed before you're under contract.
4. Potentially smoother mortgage processing
Completing important verification steps early may reduce delays later, although it does not guarantee a faster closing.
5. Better loan program evaluation
Pre-approval provides an opportunity to assess conventional, FHA, VA, jumbo, and other applicable mortgage options.
Mortgage Pre-Qualification vs. Pre-Approval: Side-by-Side Comparison
Feature | Pre-Qualification | Pre-Approval |
Purpose | Preliminary borrowing estimate | More detailed financing assessment |
Income review | Often self-reported | Typically documented or verified |
Credit review | Varies by lender | Usually includes credit review |
Asset verification | Often limited | Typically more extensive |
Processing time | Often relatively quick | Depends on lender and documentation |
Seller confidence | Generally lower | Generally stronger |
Loan commitment | No | No |
Best use | Early planning | Preparing to make an offer |
Important: Neither pre-qualification nor pre-approval guarantees final mortgage approval.
7 Key Differences Every Homebuyer Should Understand
1. The Level of Financial Verification
Pre-qualification commonly begins with estimates. Pre-approval typically involves a more detailed review of your actual financial documentation.
2. Credit Review Requirements
Some pre-qualification processes use soft credit inquiries, while pre-approval commonly requires a hard credit inquiry.
A hard inquiry may have a temporary effect on your credit score. Ask your mortgage professional what type of inquiry will be performed.
3. Accuracy of Your Estimated Loan Amount
A pre-qualification estimate may change significantly when a lender verifies your income, debts, assets, and credit history.
Pre-approval generally provides a better-supported estimate, although it remains conditional.
4. Strength of Your Purchase Offer
In a competitive housing market, sellers may prefer buyers who have already completed a more substantial financing review.
A pre-approval letter can help demonstrate that you're taking the purchase seriously.
5. Mortgage Program Selection
Pre-qualification may identify potential financing options.
Pre-approval can provide a more detailed assessment of whether you appear to meet specific loan program requirements.
6. Potential Closing Delays
A more thorough review before making an offer may identify issues that otherwise would not surface until after the purchase contract is signed.
7. Readiness to Purchase
Pre-qualification is often appropriate when you're exploring the market.
Pre-approval is generally the better choice when you're preparing to make an offer.
How Much House Can You Afford?
One of the biggest mistakes homebuyers make is confusing the maximum mortgage amount they might qualify for with the amount they should comfortably spend.
Consider this hypothetical example:
A borrower receives a pre-approval indicating potential eligibility for a $450,000 home purchase.
However, after reviewing projected property taxes, homeowners insurance, mortgage insurance, and other expenses, the borrower determines that a $375,000 home better supports their financial goals.
The right purchase price isn't necessarily the highest amount a lender will approve.
At Medallion Funds, our objective is to help borrowers evaluate financing options within the context of their broader financial circumstances.
What Documents Do You Need for Mortgage Pre-Approval?
Although requirements vary by lender and loan program, many borrowers should be prepared to provide:
·Recent pay stubs
·W-2 forms from the previous two years
·Federal tax returns, when required
·Recent bank statements
·Documentation of additional income
·Information about existing mortgage obligations
·Identification and employment details
·Documentation of gift funds, when applicable
What About Self-Employed Borrowers?
Self-employed borrowers may need additional documentation, including business tax returns, profit-and-loss statements, or business bank statements.
Certain alternative-documentation mortgage programs may be available for qualified borrowers who do not fit traditional income-verification requirements.
A mortgage broker can help assess which options may be appropriate.
Does Mortgage Pre-Approval Guarantee Final Approval?
No.
Even after receiving a mortgage pre-approval letter, several items may still need to be completed.
These can include:
·Property appraisal
·Title review
·Property insurance verification
·Final income and employment verification
·Updated asset documentation
·Final underwriting approval
·Satisfaction of lender conditions
Significant financial changes between pre-approval and closing can affect eligibility.
For example, opening new credit accounts, financing a vehicle, changing employment, or taking on additional debt could create complications.
Avoid major financial changes during the mortgage process without first consulting your mortgage professional.
How Long Does Mortgage Pre-Approval Last?
Many mortgage pre-approval letters are issued with validity periods of approximately 30 to 90 days.
However, the exact period depends on the lender, loan program, credit report requirements, and supporting documentation.
If your home search extends beyond the expiration date, updated documentation or a new credit review may be required.
Should You Get Pre-Qualified or Pre-Approved First?
The best approach depends on your timeline.
If you're six months away from buying:
A preliminary pre-qualification may help you evaluate affordability, identify potential issues, and create a financial preparation plan.
If you're planning to purchase within the next 30 to 90 days:
A more comprehensive pre-approval is generally preferable.
If you're actively making offers:
You should strongly consider obtaining a current pre-approval letter before submitting an offer.
Why Work With a Mortgage Broker Instead of Going Directly to One Bank?
A traditional bank generally evaluates mortgage applications using the loan products and lending guidelines available through that institution.
A mortgage broker can help borrowers explore financing options from multiple wholesale lending sources.
This may be especially useful for borrowers with:
·Nontraditional income
·Self-employment earnings
·Significant student loan debt
·Jumbo mortgage requirements
·Investment property financing needs
·Unique credit or asset circumstances
At Medallion Funds, we focus on understanding the borrower's complete financial picture before evaluating available mortgage structures.
The objective isn't simply to obtain a pre-approval letter. It's to identify financing that aligns with your purchase and financial goals.
Frequently Asked Questions
Can I get pre-approved without finding a house?
Yes. Many borrowers obtain mortgage pre-approval before identifying a specific property. Final approval will still depend on the property and other outstanding conditions.
Does mortgage pre-qualification hurt my credit score?
Not necessarily. Some lenders use a soft inquiry or do not check credit during preliminary pre-qualification. Ask about the inquiry type before proceeding.
Can I get pre-approved with a low credit score?
Possibly. Eligibility depends on the loan program, credit history, income, debts, available assets, and other underwriting factors.
Can I obtain pre-approval from more than one lender?
Yes. Comparing mortgage options can help borrowers evaluate rates, fees, programs, and service levels. Credit scoring models may treat multiple mortgage-shopping inquiries within an applicable window as a single inquiry, although the rules vary by model.
Is a pre-approval letter a guarantee that my loan will close?
No. Final mortgage approval remains subject to underwriting, property review, and satisfaction of lender conditions.
How early should I get mortgage pre-approved?
For borrowers actively preparing to purchase, beginning the pre-approval process before touring homes or making offers is often beneficial.
Final Thoughts: Preparation Creates Better Homebuying Decisions
Understanding the difference between mortgage pre-qualification and pre-approval can help you avoid confusion and prepare for the homebuying process.
Pre-qualification is a valuable initial planning tool.
Pre-approval typically provides a more substantial assessment of your financing eligibility and can help position you as a better-prepared buyer.
Before you fall in love with a home, make sure you understand your financing options.
Ready to Discuss Your Mortgage Options?
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds.
Whether you're purchasing your first home, upgrading to a larger property, or evaluating alternative mortgage programs, we can help you explore available financing solutions.
Website: https://billrapponline.com/
YouTube: https://www.youtube.com/@billrapp-medallion-funds
NMLS #228246
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice